The government paused Companies House's profit and loss filing rule for small firms. Its own review response, published the same day, says the data has "enormous value" for catching economic crime.
Estimated reading time: 7 minutes

In short. On 23 October 2026 the government published its response to the Small Business Regulatory Taskforce, stating plainly that "there is enormous value in Companies House having access to P&L accounts for all companies, as it supports wider efforts to tackle economic crime by improving corporate transparency" [2] (p.8). Two paragraphs later, the same document confirms the government has "decided to pause implementing the P&L filing requirement" [2] (p.8), with no resumption date, only a promise to "provide further details about this in due course" [2] (p.8). A June 2026 announcement that had recommitted to the same duty, and explained that Companies House, law enforcement and HMRC would still see the data even if the public could not, was withdrawn the same day [3]. Two documented mistakes: four stars.
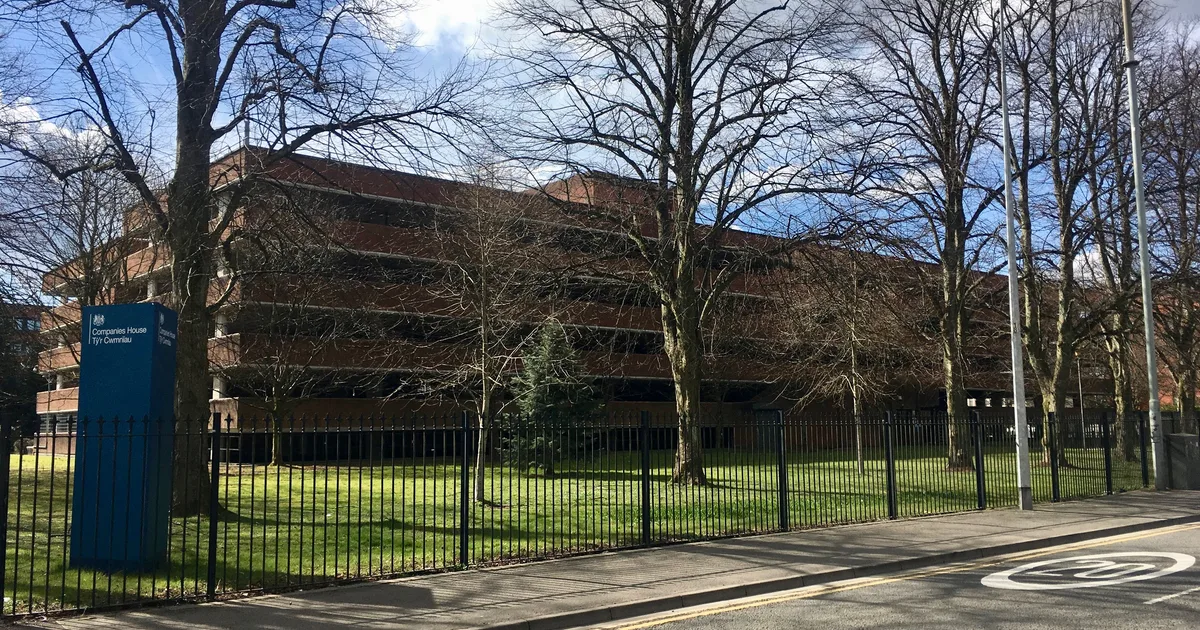
Companies House's Cardiff headquarters sits behind iron railings on Crown Way, the registry of record for every one of the small and micro companies that make up most of the firms on its books. The Economic Crime and Corporate Transparency Act 2023 was meant to change what that registry actually knows about them. Its own outline transition plan describes the Act's purpose without qualification: to "reform the role of Companies House and improve transparency over UK companies and other legal entities to strengthen our business environment, support our national security and disrupt economic crime" [4]. One of the specific duties built to deliver that was a requirement for small and micro-entity companies to start filing full profit and loss accounts, the same disclosure larger companies already make, rather than the stripped-down "abridged" accounts that currently let many of them keep turnover and profit out of the public record entirely.
That duty has now been paused, not scaled back, not delayed to a named date, paused, on the government's own account of why it matters.
The claims, tested
| What the government said, and when | What the same government said next | Verdict |
|---|---|---|
| 9 June 2026: "the government will proceed with the accounts reforms, including... requiring small companies and micro entities to file profit and loss accounts with Companies House... Where a company opts out of publishing its profit and loss accounts, Companies House, law enforcement and HMRC will still have access to help identify and tackle fraud, economic crime and tax evasion" [3] | 23 October 2026: that announcement was withdrawn outright, marked "This news article was withdrawn on 23 October 2026" [3] and replaced by one pausing the filing duty itself [1] | The June compromise kept Companies House, law enforcement and HMRC able to see the figures even where the public could not. The October pause removes the filing duty, so none of them receive the data either, a bigger rollback than the announcement describes |
| 23 October 2026, same response, same page: "there is enormous value in Companies House having access to P&L accounts for all companies, as it supports wider efforts to tackle economic crime by improving corporate transparency" [2] (p.8) | The next sentence: "We have therefore decided to pause implementing the P&L filing requirement while we explore options to streamline Companies House and HMRC filing processes... We will provide further details about this in due course" [2] (p.8) | The document states the measure's anti-fraud value and removes it in the same breath, with no timetable, no review date and no named alternative, only "in due course" |
| The Act's accounts reforms "seek to... tackle economic crime" as one of three stated goals [1] | Checked live today, the transition plan's own "From April 2028" timetable has been edited to remove the P&L requirement entirely: "Removed all references from the 'Summary of changes' under 'From April 2028'" [4] | Of the three stated goals of the accounts reforms, the one measure most directly tied to detecting fraud is the one dropped from the published timetable; the modernisation measures, software-only filing among them, proceed on schedule |
The mistakes, counted
The document states the measure's fraud-detection value, then pauses it with no date attached (1). The government's own words are not hedged: P&L access has "enormous value" for Companies House "as it supports wider efforts to tackle economic crime" [2] (p.8). Having said that, the same paragraph pauses the filing requirement that would deliver it, promising only that "further details" will follow "in due course" [2] (p.8), a phrase with no date, no review mechanism and no named owner attached to it anywhere in the response or the announcement. The Small Business Regulatory Taskforce recommendation that triggered the pause is about "duplicative filing requirements" between Companies House and HMRC [2] (p.8), a real administrative complaint, but the response does not explain why the only available fix was to stop Companies House collecting the data at all, rather than, for instance, keeping the filing duty and building the data-sharing fix the Taskforce actually asked for.
The October pause is a bigger step back than the announcement says it is (2). The 9 June 2026 announcement that the October pause replaces was explicit that even under its opt-out compromise, "Companies House, law enforcement and HMRC will still have access to help identify and tackle fraud, economic crime and tax evasion" [3]; only publication to the public register was optional, not the filing itself. The October pause removes the filing duty, meaning none of those three bodies receive the data either, for as long as the pause lasts. Neither the 23 October news announcement [1] nor the Taskforce response [2] describes this difference; both present the pause as a continuation of "balancing transparency with reducing business burden" rather than as the withdrawal of a safeguard the June announcement had specifically preserved.
Credit where due
The government did not bury this. It published a dated, 20-page written response to the Taskforce setting out its reasoning in full, rather than quietly editing the transition plan and leaving readers to notice [2]. The transition plan's own update log records the change openly, dated and described, rather than as a silent edit [4]. And the harder half of the April 2028 package, mandatory software-only filing in iXBRL format, a strengthened audit-exemption statement and the limit on shortening accounting reference periods, is confirmed as going ahead unchanged [1]. This is not a story about a reform quietly abandoned; it is a government document that makes its own case against its own decision and does not resolve the contradiction.
Verdict
Four stars, two documented mistakes. The Economic Crime and Corporate Transparency Act was built, on its own stated terms, to disrupt economic crime by improving what Companies House knows about the companies it registers. The one duty most directly aimed at that goal for the small and micro companies that make up most of the register has now been paused, not delayed to a named date, paused, in a document that in the same breath calls the data it collects of "enormous value" for exactly the purpose it is pausing.
The star score counts two documented mistakes. First, the government's 23 October 2026 response to the Small Business Regulatory Taskforce states that Companies House access to profit and loss accounts has "enormous value" for tackling economic crime, then pauses the filing requirement that would provide it, with only "further details in due course" and no resumption date, review mechanism or named owner. Second, the pause is a larger rollback than either the news announcement or the Taskforce response describes: the June 2026 commitment it replaces kept Companies House, law enforcement and HMRC able to see the data even where public disclosure was optional, while the October pause removes the filing duty itself, so none of them receive it, a difference neither document states. Two mistakes in the 1 to 3 band: four stars; the bands are on the ratings page. This piece makes no finding about the conduct of any named individual; the documents checked are institutional publications, not any one official's decision. All sources below were fetched directly on 25 October 2026 and returned HTTP 200.
Sources
- Companies House update to accounts filing from April 2028, GOV.UK news story, published 23 October 2026
- Government response to Small Business Regulatory Taskforce report, published 23 October 2026 (quotations page 8 of the attached PDF, "Reducing the Regulatory Burden for Small Business")
- Companies House to bring in changes to accounts filing from April 2028, GOV.UK news story, published 9 June 2026, withdrawn 23 October 2026
- Economic Crime and Corporate Transparency Act: outline transition plan for Companies House, Companies House, first published 16 October 2024, last updated 23 October 2026